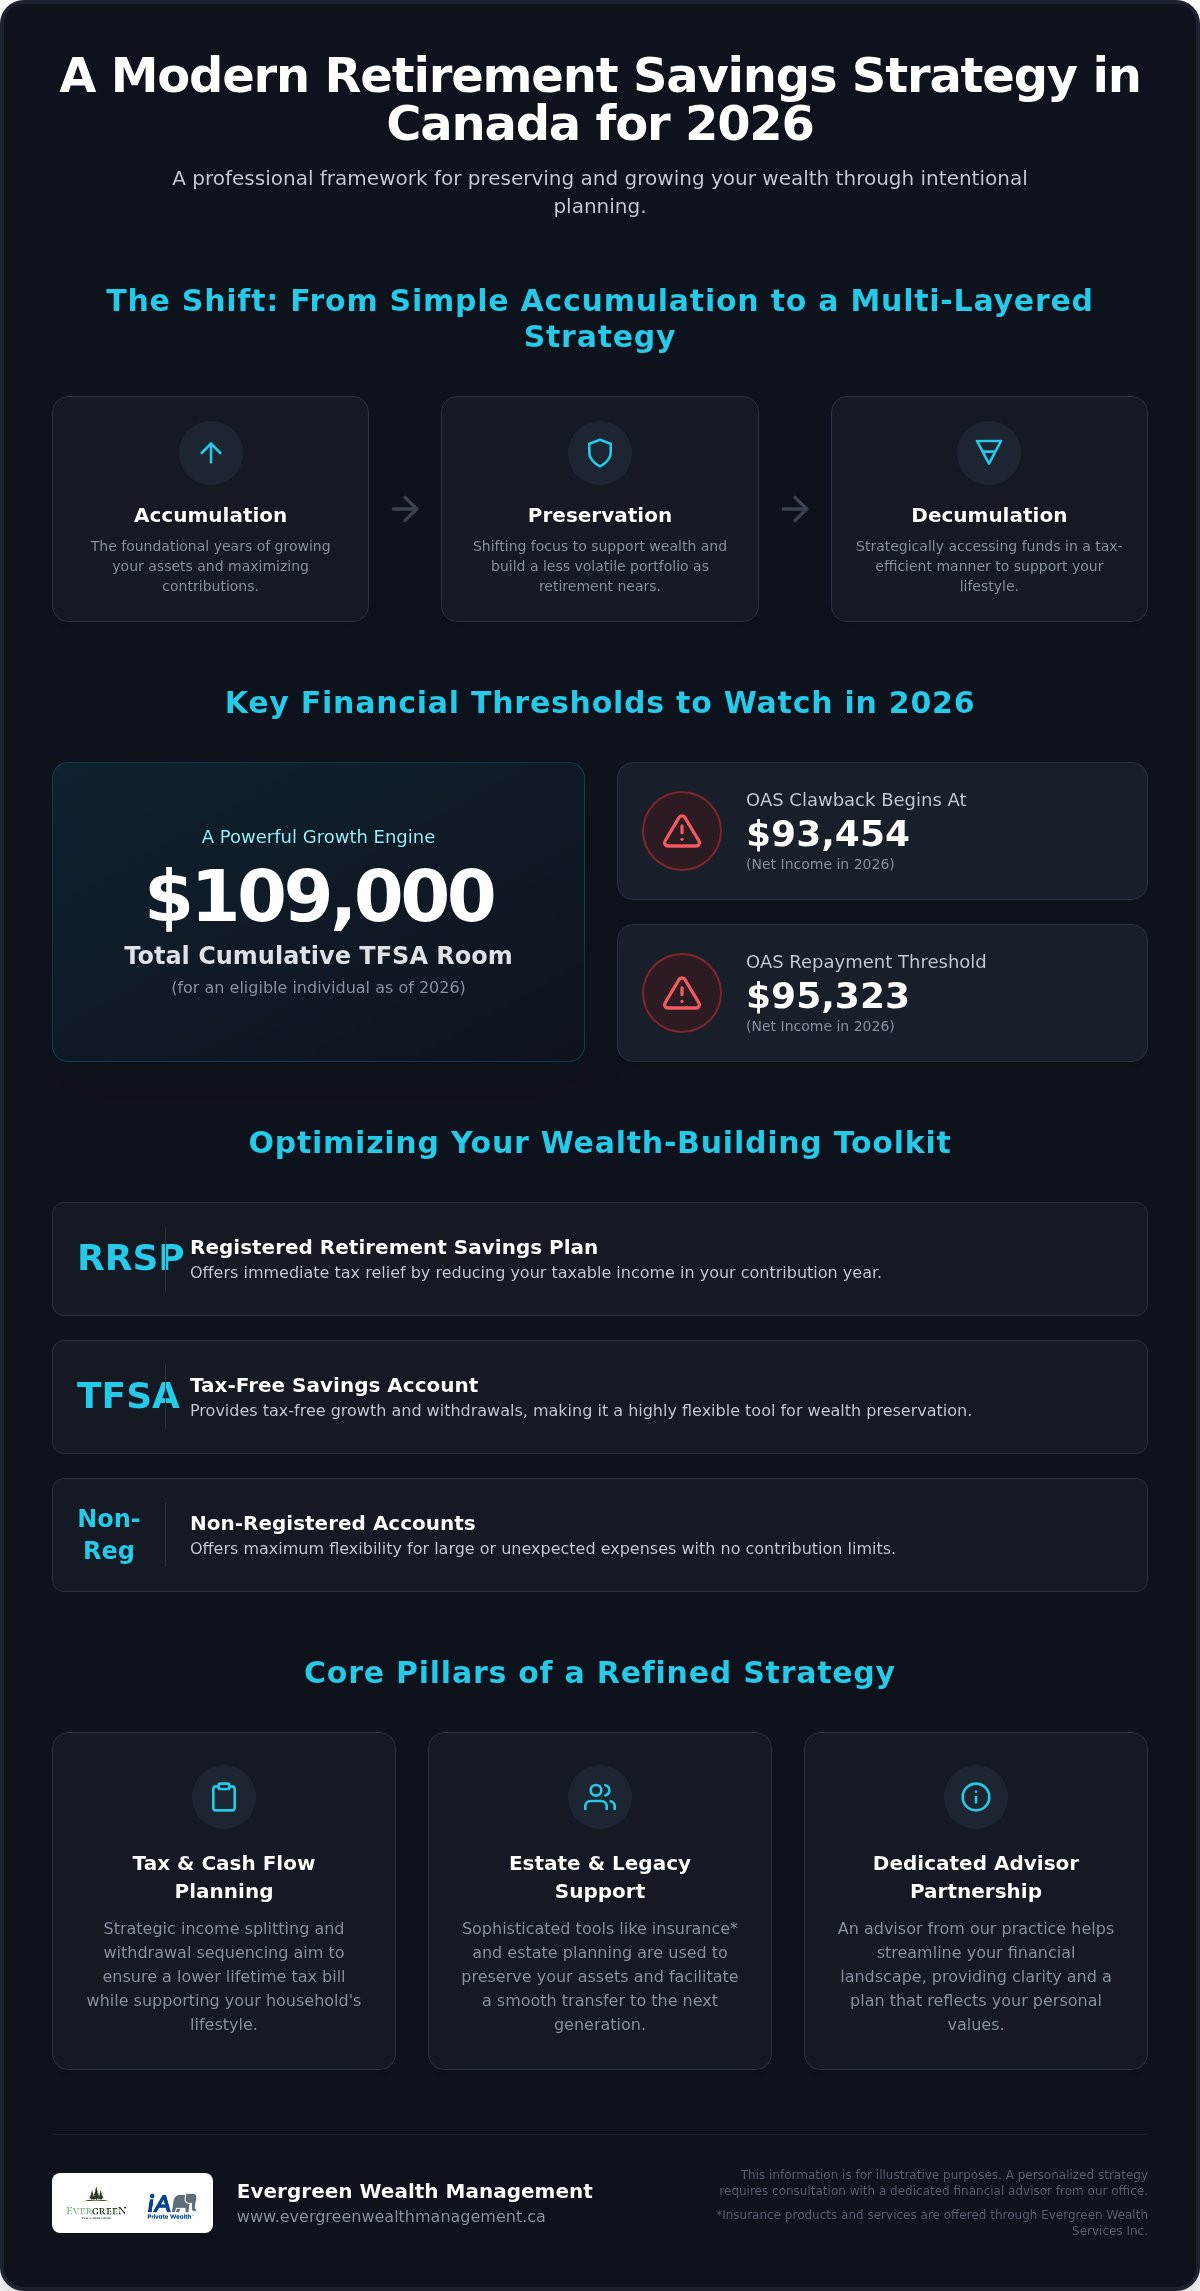
Did you know that by 2026, an eligible individual who hasn’t yet contributed to a Tax-Free Savings Account could have a total cumulative room of $109,000 as of 2026? While such opportunities exist, it’s common to feel a sense of unease when managing the complexity of multiple accounts alongside shifting tax brackets. You might worry about how market fluctuations affect your long-term growth or if the OAS clawback threshold, which begins at $93,454 in 2026, will impact your retirement income. Evergreen Wealth Management, iA Private Wealth, our advisors understand that a truly effective retirement savings strategy in Canada requires more than just accumulation; it demands a refined approach to how those assets are preserved and eventually accessed.

You deserve a simplified financial landscape that reduces daily stress and provides a clear roadmap for the years ahead. This article shares a professional planning template designed to help you build a less volatile financial future. We’ll examine a structured framework for asset allocation and decumulation that aims to ensure your wealth supports your goals. By focusing on tax-efficient transitions and intentional oversight, our office helps you move toward retirement with a sense of calm and the confidence that your legacy remains supported for the next generation.

Key Takeaways

  • Learn why it’s vital to transition from simple accumulation to a multi-layered retirement savings strategy in Canada that prioritizes preservation and decumulation.
  • Discover how to optimize the total TFSA room of $109,000 as of 2026 to create a less volatile growth engine for your portfolio.
  • Understand how strategic income splitting and cash flow planning aim to ensure a lower lifetime tax bill while supporting your household’s lifestyle.
  • Explore how insurance* and estate planning may help preserve your assets and facilitate a smooth transfer to the next generation.
  • Realize the value of partnering with a dedicated advisor at Evergreen Wealth Management to streamline your financial landscape and provide clarity at our practice.

Defining a Modern Retirement Savings Strategy in Canada for 2026

A retirement savings strategy in Canada is no longer just a savings account or a collection of investments; it’s a sophisticated, multi-layered framework. It spans the early years of accumulation, the middle years of preservation, and the final stage of decumulation. As we look toward 2026, the financial landscape feels more complex. Shifting inflation rates and evolving tax brackets mean that a passive approach won’t suffice. You need a plan that’s intentional and adaptive. A great starting point for many is the Canadian Retirement Income Calculator. This tool provides a baseline for initial assessments. However, understanding the broader Canadian Pension System Overview is also key to realizing how public and private components fit together. Our goal is to help you build a less volatile portfolio that supports your vision for the future.

The Shift from Simple Savings to Strategic Wealth Management

Years ago, simply contributing to an RRSP felt like enough. Today, professional-level planning requires moving beyond basic contributions. It’s about looking at the whole picture. A dedicated advisor helps you identify hidden gaps in your current retirement savings strategy in Canada. At Evergreen Wealth Management, we focus on creating a simplified financial landscape. Our office aims to ensure a streamlined transition between your working years and your retirement. We prioritize the human element. We make sure your plan reflects your personal values rather than just cold data. This personalized approach allows for a level of refinement that self-directed trading often misses.

Setting Objectives for the 2026 Financial Year

If you’re in your 50s, 2026 is a pivotal year for setting clear milestones. This is the time to maximize catch-up contributions and refine your tax efficiency. One critical factor to watch is the OAS repayment threshold, which is $95,323 in 2026. If your net income exceeds this amount, you may face benefit clawbacks. This makes proactive income planning essential to preserve your hard-earned wealth. Knowing when to start retirement planning in Canada can make a significant difference in how you manage these thresholds. By organizing your assets now, our practice helps you prepare for a future that feels both orderly and optimistic.

Optimizing Registered and Non-Registered Accounts in Your Strategy

Choosing the right vehicles for your wealth is like selecting the right soil for a garden. In 2026, a robust retirement savings strategy in Canada relies on a balanced mix of RRSPs, TFSAs, and non-registered accounts. Each serves a distinct purpose. RRSPs offer immediate tax relief, while TFSAs provide tax-free growth. Non-registered accounts offer the flexibility needed for large, unexpected expenses. For a deeper look at how these sources interact, you can review Morningstar’s Comprehensive Guide to Retirement Income. This integrated approach helps create a less volatile financial foundation that supports your long-term vision.

Maximizing the TFSA for Long-Term Flexibility

The Tax-Free Savings Account has evolved into a powerhouse for wealth preservation. By 2026, the total TFSA room of $109,000 as of 2026 allows for significant tax-free compounding. A focused professional doesn’t just treat this as a savings bucket. Instead, they view it as an active growth engine. Unlike the RRSP, withdrawals here don’t trigger tax or impact government benefits. You can find the latest CRA rules for TFSAs to see how these limits apply to your specific situation. Moving beyond a "save and forget" mindset allows you to use this room for higher-growth assets that might otherwise face heavy taxation.

Strategic RRSP Contributions and the 2026 Limits

The RRSP remains a cornerstone of tax-deferred growth. For the 2026 tax year, the RRSP contribution limit is $33,810. This is a valuable tool for those in high tax brackets today. However, it’s not without risks. Withdrawing large sums in later years can push you into a higher tax bracket or trigger clawbacks. This is where timing becomes vital. An advisor at Evergreen Wealth Management can help you decide when to take deductions to optimize your multi-year tax horizon. We look at your current income versus your projected retirement income to find the most efficient path for contributions.

Finally, don’t overlook non-registered accounts. While they don’t offer the same tax shelters, they provide essential liquidity. This flexibility is a key part of a modern retirement savings strategy in Canada. It allows you to access funds without the rigid rules of registered plans. If you’re ready to refine your account allocation, you might consider speaking with an advisor at our office. Our practice is dedicated to helping you streamline these complex choices and move forward with clarity.

Integrating Tax and Cash Flow Planning for Wealth Preservation

Tax planning for retirement in Canada isn’t just about the current year’s return. It’s about looking at your entire lifetime tax bill. A well-constructed retirement savings strategy in Canada aims to ensure you don’t overpay the government over decades. One effective way to do this is through income splitting. This practice allows couples to balance their tax burden, often moving income from a higher-earning spouse to a lower-earning one. It’s a simple yet powerful way to keep more of your wealth within the family. By aligning your income levels, you can often stay within lower tax brackets and preserve more of your hard-earned capital.

Managing your cash flow is equally vital to your long-term success. Without a plan, you might find yourself forced to sell assets during a market downturn just to cover daily expenses. This can permanently damage your portfolio’s growth potential. For a deeper look at how to structure your holdings to avoid these pitfalls, you can explore our guide on Retirement Portfolio Management in Canada. By organizing your assets properly, you can maintain a steady lifestyle without compromising your future.

The Mechanics of Tax-Efficient Income Streams

The order in which you withdraw funds from your various accounts matters. A focused professional at our office can help you sequence these payments from RRSPs, TFSAs, and non-registered accounts to preserve your capital for as long as possible. We also watch the OAS repayment threshold closely. In 2026, that threshold is $95,323. If your income climbs too high, your government benefits could be reduced or "clawed back." By structuring your income streams carefully, an advisor aims to ensure you stay below these limits while maximizing the 2026 personal tax credits available to you. These credits are a vital factor in your annual cash flow planning, as they help reduce your overall tax liability and keep your plan on track.

Preserving Capital Through Market Cycles

Market stress is a natural part of the economic cycle. However, it shouldn’t dictate your lifestyle or your peace of mind. A less volatile withdrawal strategy helps you stay the course when things get bumpy. By having a clear cash flow plan, you reduce the emotional pressure that comes with short-term market fluctuations. You aren’t reacting to headlines; you’re following a deliberate, professional process. This is where the value of a dedicated advisor truly shines. Our practice provides the "calm in the storm," helping you maintain your long-term vision while others might be tempted to make hasty decisions. We focus on the big picture so you can focus on enjoying your retirement. This methodical approach helps support your financial health, regardless of what the broader markets are doing. For those who have already transitioned out of the workforce, our post-retirement planning guide for Canada in 2026 offers a detailed roadmap for managing income, taxes, and legacy in this next chapter.

The Essential Role of Insurance* and Estate Planning

Insurance* is often misunderstood as merely a fallback for the unexpected. In a sophisticated retirement savings strategy in Canada, it’s actually a vital tool for wealth transfer and tax liability coverage. It helps cover significant costs that arise at death, such as those on a family cottage or corporate shares. Without this foresight, heirs might be forced to sell beloved assets just to pay the CRA. By using tax-free death benefits, you can preserve the full value of your estate for the next generation. For a more detailed look at these options, you can consult our Professional Guide to Insurance* for Retirement. Our office focuses on integrating these tools so they work in harmony with your investments.

Estate planning is the final piece of a professional plan. It involves more than just a will; it requires careful coordination of beneficiary designations and the potential use of trusts. These structures help your assets bypass the costly and time-consuming probate process. At Evergreen Wealth Management, our advisors work alongside your legal professionals to keep your plan cohesive and clear. This collaborative approach aims to ensure that your intentions are carried out exactly as you envisioned, providing a simplified path for your loved ones during a difficult time.

Preserving Your Legacy with Strategic Insurance* Solutions

Dedicated advisors often use insurance* to equalize inheritances among heirs. If one child is taking over a family business while another is not, a life insurance* policy can provide an equivalent cash gift to the second child. This approach helps maintain family harmony and supports a less volatile transition of wealth. It also provides the liquidity needed to fund terminal taxes, which supports the preservation of your primary assets. By incorporating these solutions into your retirement savings strategy in Canada, you create a layer of foresight that benefits your family for years to come.

Estate Planning: Simplifying the Transition

Having up-to-date wills and powers of attorney is a fundamental part of our practice’s philosophy. As laws and family situations change, your documents must evolve too. We recommend a thorough review every year to reflect your current reality. This process reduces anxiety and provides the "calm in the storm" for your executors. It’s about order and clarity rather than leaving things to chance.

Consider this checklist for your 2026 annual estate review:

  • Confirm that your powers of attorney for property and personal care are current.
  • Review beneficiary designations on RRSPs, RRIFs, and TFSAs to reflect current family dynamics.
  • Evaluate if a trust structure is appropriate for complex asset distributions or minor beneficiaries.
  • Update your will to reflect any changes in Canadian tax law effective as of 2026.

Our office provides the steady guidance needed to navigate these sensitive topics. If you’re ready to document your wishes and preserve your hard-earned legacy, you can reach out to an advisor at our practice to begin the process.

Retirement Savings Strategy in Canada: A Professional Planning Template for 2026

Partnering with a Professional Advisor at Evergreen Wealth Management

Managing a retirement savings strategy in Canada involves more than just selecting investments; it’s about orchestrating a symphony of moving parts. At Evergreen Wealth Management, we believe that your financial plan should be as unique as your thumbprint. Our office doesn’t rely on one-size-fits-all products. Instead, we offer a unique approach that prioritizes your personal goals and family values. A focused professional at our practice provides the "calm in the storm" when complex life transitions feel overwhelming. By visiting http://www.evergreenwealthmanagement.ca, you can explore how our methodology integrates tax planning, cash flow, portfolio management, estate preservation, and insurance* into one cohesive vision.

A Boutique Practice Focused on Your Long-Term Journey

There’s a significant difference between the institutional feel of a large corporation and the personalized attention of a boutique office. We pride ourselves on being a partner that’s deeply invested in your long-term journey. Our dedicated advisors focus on streamlining your financial landscape, which aims to ensure you have more time for what truly matters. We don’t just look at the next quarter; we look at generational continuity. By focusing on wealth preservation, we help you build a legacy that lasts. This commitment to detail allows us to catch the subtle gaps that others might miss, creating a more refined experience for every family we serve.

Taking the Next Step Toward a Less Volatile Future

Building a retirement savings strategy in Canada that stands the test of time requires a methodical discovery process. When you first connect with our office, we take the time to understand your current situation and your future aspirations. We look at all five pillars of your financial health to see where adjustments are needed. This thorough review aims to ensure your plan remains relevant through 2026 and well beyond. We don’t just set a course and walk away; we provide ongoing oversight to navigate the inevitable shifts in the economic landscape.

Your path toward a less volatile future starts with a single conversation. If you’re looking for a partner who values order, foresight, and a simplified approach to complex situations, we’re here to help. You can connect with an advisor at our practice for a professional review of your current plan. Let’s work together to create the clarity and peace of mind you deserve as you navigate the road ahead.

Embracing a Refined Path Toward Your Future

Refining your retirement savings strategy in Canada is an act of foresight that transforms complexity into clarity. We’ve explored how a multi-layered framework, from maximizing your total TFSA room of $109,000 as of 2026 to navigating tax thresholds, aims to ensure your wealth remains resilient. By integrating tax-efficient cash flow with strategic insurance* solutions, you don’t just save for the future; you preserve a legacy for the next generation.

Evergreen Wealth Management operates as a boutique practice dedicated to your long-term financial peace of mind. Our advisors provide personalized wealth management, often for retirees in Canada, focusing on estate preservation and a simplified financial landscape. We’re here to provide the steady guidance needed to support a less volatile transition into your next chapter. It’s about creating a plan that’s as intentional as the life you’ve built.

If you’re ready to move from vision to execution, we invite you to connect with an advisor at Evergreen Wealth Management to refine your strategy. Our office is here to offer the intentional oversight your journey deserves. You’ve worked hard to build your wealth; let’s work together to support it for the years ahead.

Frequently Asked Questions

What is the most tax-efficient retirement savings strategy in Canada for 2026?

The most tax-efficient retirement savings strategy in Canada for 2026 involves balancing immediate tax deductions with long-term tax-free growth. By utilizing RRSPs to lower your current taxable income and TFSAs to build a tax-free income stream, you create a flexible framework. This dual approach helps you manage different tax brackets throughout your retirement years while keeping your lifetime tax bill lower.

How does the 2026 OAS repayment threshold affect my retirement income planning?

The OAS repayment threshold is $95,323 in 2026, which means any net income above this amount triggers a recovery tax. Proactive planning aims to ensure your income stays below this level to avoid benefit clawbacks. Our advisors focus on structuring your withdrawals to keep your taxable income within an efficient range that preserves your government benefits.

Should I prioritize RRSP or TFSA contributions in my 50s?

Prioritizing RRSP or TFSA contributions in your 50s depends on your current tax bracket compared to your expected bracket in retirement. High earners often benefit from RRSP deductions now, while the TFSA offers a less volatile way to grow wealth without future tax liabilities. A dedicated advisor at our practice can help you determine the right split for your specific goals and income level.

How can insurance* be used to preserve my estate for my children?

You can use insurance* to fund terminal tax liabilities on secondary properties or corporate shares without depleting your estate’s cash reserves. This strategy supports the preservation of your assets for your children by providing a tax-free death benefit to cover the CRA’s final bill. It’s a sophisticated way to support your legacy within a broader retirement savings strategy in Canada.

What are the benefits of working with a professional advisor at a boutique office?

Working with a dedicated advisor at a boutique office like Evergreen Wealth Management, iA Private Wealth, offers a personalized mindset rather than a one-size-fits-all approach. Our practice prioritizes the human element, providing personalized oversight that larger institutions often lack. We focus on streamlining your financial landscape to reduce daily stress and provide a calm perspective during significant life transitions.

How do I minimize tax on my RRIF withdrawals in Canada?

To minimize tax on your RRIF withdrawals in Canada, consider income splitting with a spouse or sequencing withdrawals alongside non-registered funds. By keeping your annual income balanced, you can avoid being pushed into higher tax brackets. Our office helps you design a decumulation plan that aims to ensure your lifetime tax bill remains as low as possible while maintaining your lifestyle. For a comprehensive look at managing income once you’ve left the workforce, our professional guide to post-retirement planning in Canada covers RRIF strategies, CPP optimization, and more.

What is the cumulative TFSA limit for 2026?

For an eligible individual who has never contributed, there is a total TFSA room of $109,000 as of 2026. This cumulative limit provides a significant opportunity for tax-free compounding over the long term. Utilizing this room effectively is a cornerstone of a modern retirement savings strategy in Canada that focuses on tax-free income.

How does Evergreen Wealth Management support wealth preservation during market volatility?

Evergreen Wealth Management supports wealth preservation by creating less volatile portfolios and robust cash flow plans that reduce the need to sell assets during downturns. We focus on asset allocation that reduces the emotional pressure of short-term market fluctuations. Our advisors act as a "calm in the storm," helping you maintain your long-term vision even when the broader economic landscape is bumpy.

Article by

Rodney Anton

Rodney Anton is a Portfolio Manager, Senior Investment Advisor at Evergreen Wealth Management | iA Private Wealth, and an Insurance Advisor* at Evergreen Wealth Management Inc. He works with executives, professionals, and business owners to help coordinate investment strategy, tax planning, retirement income, and long-term wealth creation. Rodney focuses on building practical, personalized financial strategies that help clients preserve what they have built while identifying opportunities for growth.

Disclaimer

This information has been prepared by Rodney Anton who is a Portfolio Manager for iA Private Wealth Inc. and does not necessarily reflect the opinion of iA Private Wealth. The information contained in this article comes from sources we believe reliable, but we cannot guarantee its accuracy or reliability.

The opinions expressed are based on an analysis and interpretation dating from the date of
publication and are subject to change without notice. Furthermore, they do not constitute an
offer or solicitation to buy or sell any of the securities mentioned. The information contained
herein may not apply to all types of investors.

This content was fully or partially generated by artificial intelligence. The advisor reviewed the critical information independently.

iA Private Wealth Inc. is a member of the Canadian Investor Protection Fund and the Canadian
Investment Regulatory Organization. iA Private Wealth is a trademark and a business name
under which iA Private Wealth Inc. operates

*Insurance products and services are offered through Evergreen Wealth Management Inc., an
independent and separate company from iA Private Wealth Inc. Only products and services offered through iA Private Wealth Inc. are covered by the Canadian Investor Protection Fund

Discover more from Evergreen Wealth Management

Subscribe now to keep reading and get access to the full archive.

Continue reading