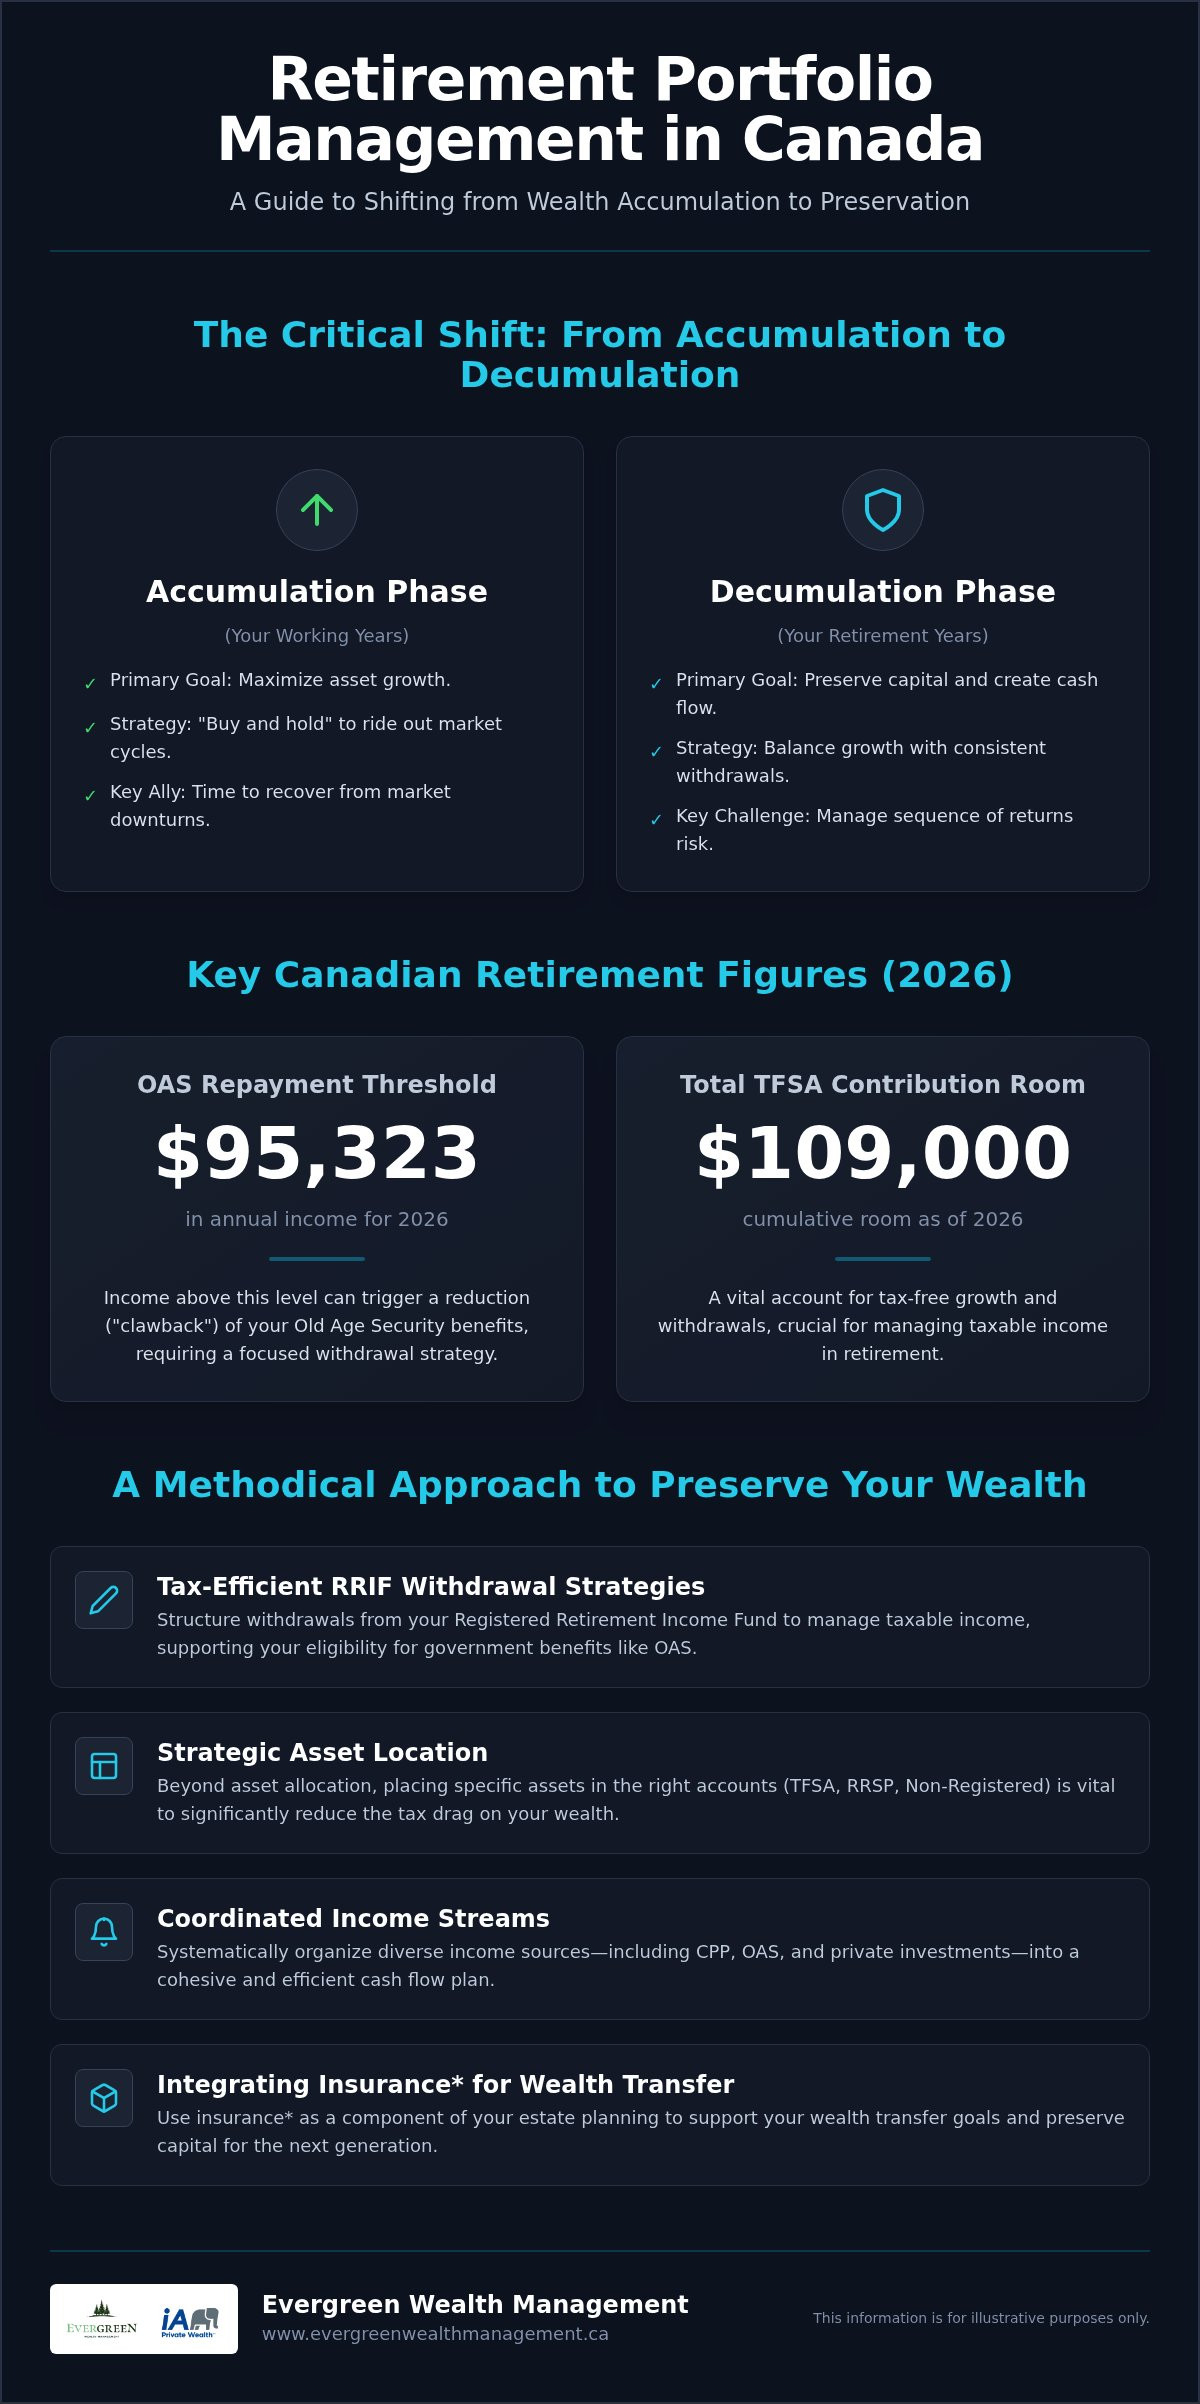
What if the very income you worked decades to build actually triggers a significant reduction in your government benefits? For many Canadians, reaching the OAS repayment threshold of $95,323 in 2026 is a bittersweet milestone that highlights the complexities of retirement portfolio management in Canada. It’s natural to feel a sense of anxiety when market volatility fluctuates or when the rules for tax-efficient RRIF withdrawals feel like a moving target. You’ve spent a lifetime accumulating wealth; now, the priority shifts to making it last.

At Evergreen Wealth Management, iA Private Wealth, our office focuses on turning that complexity into a streamlined, intentional strategy. You’ll learn how to organize your assets, minimize taxes, and realize a sustainable cash flow through professional retirement portfolio management in Canada. Your dedicated advisor will help you maximize the total TFSA room of $109,000 available as of 2026 and use insurance* to support your legacy.

Key Takeaways

  • Understand how the transition from accumulation to decumulation requires a fundamental shift in retirement portfolio management in Canada to prioritize cash flow and wealth preservation.
  • Learn how to structure RRIF withdrawal strategies in Canada to manage taxable income and avoid the OAS repayment threshold of $95,323 in 2026.
  • Discover the importance of asset location and how to utilize the total TFSA room of $109,000 available as of 2026 to support your long-term growth.
  • See how integrating insurance* into your estate planning can support your wealth transfer goals and help in preserving your capital for the next generation.
  • Find out how a dedicated advisor at Evergreen Wealth Management uses a methodical practice to streamline your financial landscape and provide clarity.

Why Portfolio Management for Retirement in Canada Requires a Dedicated Approach

The transition from saving for the future to living on those savings represents one of the most profound shifts in your financial life. For decades, the goal was simple: accumulate as much as possible. However, as you approach your 60s, the focus must pivot toward decumulation. Effective retirement portfolio management Canada isn’t just about picking high-performing assets; it’s about engineering a sustainable income stream that lasts through your entire life. This shift requires a professional level of oversight to manage the risks that become magnified when you’re no longer contributing to your accounts.

Market volatility feels different when you’re actively withdrawing funds. A sudden downturn early in retirement can significantly impact the longevity of your capital if your withdrawals aren’t managed with foresight. At Evergreen Wealth Management, our office focuses on creating order within this complex landscape. We prioritize clarity and precision to help you move from a state of accumulation to a state of preservation with confidence.

The Transition from Growth to Preservation

The "buy and hold" strategy that served you well in your 40s often lacks the nuance required for your 60s. During your working years, time is your greatest ally, allowing you to ride out market cycles. In retirement, you need to realize a delicate balance between continued capital growth and the necessity for consistent cash flow. An advisor at our practice can help identify specific risks, such as sequence of returns risk, that could impact your long-term vision. By shifting the focus toward wealth preservation, we support your ability to maintain your lifestyle without the fear of outliving your capital.

Simplifying the Canadian Retirement Landscape

Organizing various income streams is a cornerstone of a focused retirement plan. Many retirees find themselves balancing private investments with Pensions in Canada, including the Canada Pension Plan (CPP) and Old Age Security (OAS). Without a systematic methodology, these layers can become disjointed, leading to tax inefficiencies or missed opportunities for optimization.

Evergreen Wealth Management provides a personalized strategy to coordinate these benefits with your private wealth. This level of coordination is essential to support your long-term cash flow and reduce the anxiety often associated with significant life transitions. By streamlining your financial landscape, we help you focus on the human element of retirement, rather than getting lost in institutional data. Our goal is to provide a sense of composure through a well-considered strategy that evolves with you through 2026 and beyond.

Structuring a Retirement Savings Strategy in Canada for 2026

While many investors focus heavily on asset allocation, the concept of asset location is equally vital for those refining their retirement portfolio management Canada. Placing the right assets in the right accounts can significantly reduce the tax drag on your wealth. For instance, non-registered accounts are often better suited for investments that generate Canadian dividends or capital gains due to their favourable tax treatment. Meanwhile, interest-bearing assets might be more appropriate within registered plans where their growth is sheltered from immediate taxation.

Maximizing your available contribution room is a foundational step in building a resilient strategy. According to the total cumulative TFSA room has reached $109,000 as of 2026 for individuals who have been eligible since the program’s inception. By utilizing these accounts effectively, you can realize a more streamlined financial landscape that prioritizes long-term growth and tax efficiency.

The Role of RRSPs and TFSAs in Portfolio Design

Determining the optimal order of withdrawals between your RRSP and TFSA is a pivot point that can help preserve your capital for future generations. A focused strategy looks at your current tax bracket versus your expected future bracket to decide which account to tap first. This methodical approach helps you keep more of your hard-earned money while coordinating with Canadian public pensions to minimize unnecessary clawbacks. The $109,000 TFSA contribution room as of 2026 serves as a key pillar of tax-free growth and flexibility for Canadian retirees.

Managing Market Volatility with Focused Diversification

To support portfolio endurance, you must move beyond a simple mix of stocks and bonds. A dedicated advisor at our practice looks for ways to realize a more robust portfolio by exploring asset classes that don’t always move in tandem with broader equity markets. Integrating principles of retirement portfolio management in Canada into your asset mix involves a disciplined rebalancing process. This systematic approach reduces the emotional stress of market swings and keeps your long-term vision on track. If you’re ready to see how these strategies can be tailored to your unique situation, you might consider reaching out to discuss your strategy with our office.

Tax-Efficient RRIF Withdrawal Strategies in Canada

Transitioning from an RRSP to a Registered Retirement Income Fund (RRIF) is a significant milestone that requires careful timing. While the law requires this conversion by the end of the year you turn 71, effective RRIF withdrawal strategies in Canada often begin much earlier. A proactive approach to retirement portfolio management in Canada allows you to control your taxable income levels before mandatory minimums take effect. This foresight helps avoid tax spikes that can occur if you’re forced to withdraw more than you actually need for your lifestyle.

The Government of Canada’s guide to retirement planning highlights the importance of understanding how these withdrawals interact with other income sources. At Evergreen Wealth Management, our practice focuses on helping you organize these cash flows to maintain a steady lifestyle while keeping your tax bill as low as possible.

Mitigating the OAS Clawback

One of the most critical figures for retirees is the Old Age Security repayment limit. Specifically, the OAS repayment threshold is $95,323 in 2026. If your net world income exceeds this amount, you’ll be required to repay 15 cents for every dollar over the limit. To support your income while staying below this threshold, a dedicated advisor might suggest income splitting with a spouse or partner. This methodical strategy can help a couple realize a more balanced tax profile, potentially preserving thousands of dollars in benefits that would otherwise be lost to the clawback.

Balancing Registered and Non-Registered Income

Determining which accounts to draw from first is a complex puzzle. Drawing from non-registered accounts early in retirement may allow your RRSP or RRIF to continue growing tax-deferred, but this isn’t always the most efficient path. Sometimes, taking modest RRIF withdrawals before age 71 can reduce the size of the account later, lowering future mandatory payments and supporting your long-term wealth preservation.

Annual reviews are essential to adjust for changing tax laws and your evolving personal needs. Our office uses a systematic approach to evaluate your situation every year, making sure your strategy remains aligned with your vision for retirement portfolio management Canada. By streamlining the interplay between your various accounts, we help you keep more of your hard-earned money and preserve your capital for your heirs.

Integrating Insurance* for Comprehensive Wealth Preservation

Many investors mistakenly believe that insurance* is a tool primarily for the accumulation phase of life. In reality, it serves as a critical buffer within a sophisticated strategy for retirement portfolio management Canada. As you shift toward wealth preservation, the role of insurance* evolves from income replacement to a mechanism that supports the continuity of your estate. By integrating these solutions, you can preserve the value of your assets against the corrosive effects of taxes and unforeseen costs that often arise later in life.

At Evergreen Wealth Management, our office looks at your financial landscape through a wide lens. We realize that a portfolio is only as strong as its weakest link. By addressing potential liabilities before they arise, we help you maintain a sense of composure as you navigate the human element of aging. This methodical approach allows us to prioritize your peace of mind over cold data.

Preserving Your Legacy with Life Insurance*

One of the most significant hurdles in wealth transfer is the tax liability triggered upon the passing of a second spouse. This often includes capital gains taxes on secondary properties, such as a family cottage, or a private business. Without liquid funds available, heirs might be forced to sell these cherished assets just to pay the Canada Revenue Agency. Using life insurance* provides a focused way to fund these liabilities, supporting your heirs in receiving their full intended inheritance.

This strategy is a cornerstone of effective wealth management for retirees in Canada. It allows you to preserve your capital for the next generation without depleting the investments you need for your own cash flow. For a deeper look at how these tools function within a modern plan, you can refer to our professional guide to insurance* for retirement in Canada (2026).

Supporting Your Plan Against Health Risks

The financial foundation of a retirement plan can be quickly eroded by the rising costs of long-term care. While government programs provide some support, the desire for high-quality, private care often requires significant personal funding. Integrating critical illness or health insurance* into your strategy helps preserve your portfolio from being drained by these health-related crises. It creates a dedicated pool of capital that is separate from your primary income streams.

Our practice focuses on creating a plan that accounts for more than just numbers on a spreadsheet. We recognize that aging is a personal journey, and having the right coverage in place reduces the anxiety associated with potential health declines. This systematic approach supports your long-term vision and provides clarity for your family members. If you’re concerned about how health risks might impact your legacy, we invite you to reach out to an advisor at our office to discuss a personalized preservation strategy.

Retirement Portfolio Management in Canada: A Professional Guide to Wealth Preservation (2026)

Designing a Personalized Strategy with Evergreen Wealth Management

Evergreen Wealth Management provides a tailored approach that looks beyond the surface of simple investment picking. While DIY platforms often suggest that low-fee funds are the only factor to consider, this perspective misses the critical interplay between tax, cash flow, and estate coordination. Effective retirement portfolio management Canada requires a high level of technical competence to streamline these moving parts into a single, cohesive strategy. Our practice focuses on creating order where there is often confusion, allowing you to focus on the human element of your retirement journey.

Choosing an advisor for wealth management for retirement in Canada means finding a partner that aligns with your values and long-term vision. A dedicated advisor at our office works with you to realize your goals, moving at a measured pace that builds confidence step-by-step.

The Value of Professional Portfolio Management

A systematic methodology helps you stay focused when market volatility fluctuates. Unlike a large institutional environment where you might feel like a data point, our boutique practice prioritizes a deeply personal relationship. We believe that professional oversight is essential to manage the complex transitions discussed earlier, such as staying below the OAS repayment threshold of $95,323 in 2026. By coordinating your RRIF withdrawals and insurance* needs, we support your ability to maintain a lasting legacy without compromising your current lifestyle.

Your Next Steps Toward Financial Clarity

Beginning the process of organizing your retirement portfolio starts with a simple conversation. During a personalized consultation at our office, we’ll review your current landscape and identify areas where we can streamline your accounts for better efficiency. It’s an opportunity to move from a broad vision to a grounded, process-oriented plan. We don’t rush the process; we take the time to understand the nuances of your situation.

Significant life transitions don’t have to feel overwhelming. Our goal is to be a steady presence, helping you realize a plan for retirement portfolio management Canada that supports your lifestyle today and your family tomorrow. The first step toward preserving your wealth is to establish a clear, intentional strategy that accounts for the total TFSA room of $109,000 available as of 2026 and beyond.

Realize Your Vision for a Lasting Legacy

Organizing a retirement strategy is about more than just numbers; it’s about finding clarity in a complex environment. By coordinating RRIF withdrawals to stay below the OAS repayment threshold of $95,323 in 2026 and utilizing the total TFSA room of $109,000 as of 2026, you can create a more streamlined financial future. These steps are foundational to professional retirement portfolio management Canada. Integrating insurance* and focused tax planning allows you to preserve your capital while supporting the lifestyle you’ve worked so hard to achieve.

At Evergreen Wealth Management, our practice is dedicated to providing a human-first approach that prioritizes your peace of mind. Our dedicated advisors focus on tax-efficient wealth preservation and the comprehensive integration of portfolio and insurance* solutions. We’re here to help you move from a broad vision to a grounded, intentional execution. Contact our Evergreen Wealth Management office to realize your personalized retirement strategy today. We look forward to supporting your journey toward a refined and confident future.

Frequently Asked Questions

What is the best retirement portfolio management strategy for Canadians in 2026?

The best strategy focuses on the transition from asset growth to sustainable decumulation and wealth preservation. In 2026, this involves a methodical balance between capital growth and consistent cash flow. You’ll need to organize your assets to account for inflation while prioritizing tax efficiency. A dedicated advisor at Evergreen Wealth Management can help you realize a plan that coordinates your private investments with government benefits to support your long-term vision.

How much TFSA contribution room is available as of 2026?

For individuals who have been eligible since 2009, the total TFSA room of $109,000 as of 2026 is available. This includes the annual limit increase of $7,000 for the 2026 calendar year. Utilizing this room is a key pillar of retirement portfolio management Canada, as it allows your investments to grow and be withdrawn without triggering additional tax liabilities or affecting income-tested benefits.

What is the OAS repayment threshold for the 2026 tax year?

The OAS repayment threshold is $95,323 in 2026. If your net world income exceeds this figure, you’ll be required to repay a portion of your Old Age Security benefits at a rate of 15%. Staying below this limit requires a focused approach to income timing, especially when managing mandatory RRIF withdrawals that might otherwise push you into a higher tax bracket.

How can I minimize tax on my RRIF withdrawals in Canada?

Minimizing tax on RRIF withdrawals involves strategic timing and the use of income splitting with a spouse. You might consider making withdrawals before the age of 71 to reduce the total balance of the account, which can lower your future mandatory minimums. Our practice focuses on streamlining these withdrawals alongside your non-registered assets to preserve your capital and support a more efficient tax profile throughout your retirement years.

Do I need insurance* as part of my retirement portfolio management?

Integrating insurance* is often essential to preserve the value of your estate and support your heirs. Life insurance* can fund significant tax liabilities on secondary properties or businesses, while health-related insurance* supports your portfolio against the rising costs of long-term care. At Evergreen Wealth Management, we include these solutions to create a comprehensive buffer that accounts for the human element of aging, not just investment returns.

What are the benefits of professional wealth management for retirees in Canada?

Professional wealth management for retirees in Canada provides a systematic methodology to coordinate tax planning, estate goals, and cash flow needs. A dedicated advisor helps you navigate complex transitions, such as the shift to RRIF withdrawals, with professional composure. This level of oversight helps reduce anxiety by creating an organized financial landscape, allowing you to focus on your lifestyle rather than the technical details of portfolio management.

How does income splitting work for Canadian retirees?

Income splitting allows you to allocate up to 50% of your eligible pension income to your spouse or common-law partner for tax purposes. This strategy is particularly effective for managing the OAS repayment threshold of $95,323 in 2026 by balancing your combined income. It’s a focused way to lower your household’s overall tax bill and support the longevity of your retirement savings through more efficient cash flow.

Can I manage my own retirement portfolio or should I hire an advisor?

While DIY management works for simple accumulation, the decumulation phase involves intricate tax laws and estate considerations that often require a professional approach. Hiring an advisor at our office provides you with a dedicated partner who understands the nuances of the Canadian landscape. We focus on streamlining complex situations to provide clarity and peace of mind, helping you realize a strategy that preserves your wealth for future generations.

Article by

Rodney Anton

Rodney Anton is a Portfolio Manager, Senior Investment Advisor at Evergreen Wealth Management | iA Private Wealth, and an Insurance Advisor* at Evergreen Wealth Management Inc. He works with executives, professionals, and business owners to help coordinate investment strategy, tax planning, retirement income, and long-term wealth creation. Rodney focuses on building practical, personalized financial strategies that help clients preserve what they have built while identifying opportunities for growth.

Disclaimer

This information has been prepared by Rodney Anton who is a Portfolio Manager for iA Private Wealth Inc. and does not necessarily reflect the opinion of iA Private Wealth. The information contained in this article comes from sources we believe reliable, but we cannot guarantee its accuracy or reliability.

The opinions expressed are based on an analysis and interpretation dating from the date of
publication and are subject to change without notice. Furthermore, they do not constitute an
offer or solicitation to buy or sell any of the securities mentioned. The information contained
herein may not apply to all types of investors.

This content was fully or partially generated by artificial intelligence. The advisor reviewed the critical information independently.

iA Private Wealth Inc. is a member of the Canadian Investor Protection Fund and the Canadian
Investment Regulatory Organization. iA Private Wealth is a trademark and a business name
under which iA Private Wealth Inc. operates

*Insurance products and services are offered through Evergreen Wealth Management Inc., an
independent and separate company from iA Private Wealth Inc. Only products and services offered through iA Private Wealth Inc. are covered by the Canadian Investor Protection Fund

Discover more from Evergreen Wealth Management

Subscribe now to keep reading and get access to the full archive.

Continue reading